Timing Models – ROC Shock Lingers, SPY Follows Thru on Outside Week, Breadth Models Remain Bullish

See the Weekend Post for Current Chartbooks

The medium-term indicators and breadth models are still bullish, but the ROC Shock in early September and some waning breadth indicators argue for at least a correction of the March-September advance. I covered the ROC Shock in detail last week and will review the findings. First, keep in mind that the character of the market (SPY) changed in January 2018 as the swings became bigger and 52-week lows were interspersed with 52-week highs. Big swings and volatility are the order of the day for now.

The current swing remains up, but early signs of a reversal are taking shape. First, there were signs of excess in late August and early September because SPY was more than 15% above its 200-day SMA and QQQ was more than 20% above. Second, SPY formed a big spinning top candlestick and outside week three weeks ago (red shading). Third, SPY followed through on this outside week with a 2% decline the following week (follow through). Fourth, there was an outsized decline as the 5-day Rate-of-Change exceeded -5%.

The chart above recaps the outsized decline with the red shading showing 5-day declines greater than 5% and the gold arrows showing when these declines occur after a 52-week high. The outsized declines in February 2018 and August 2019 led to extended corrective periods (10 weeks), while the outsized declines in October 2018 and February 2020 led to bear markets. The call now is for a corrective period that could last until November.

The breadth models are not designed to pick up corrections and remain bullish overall. The medium-term trend indicators are more sensitive, but the majority remain bullish. SPY fell around 7% in early September and then moved sideways the last week or so. Coming off of a new high and big advance, this is not enough weakness to affect High-Low Lines, Bullish Percent Indexes, Silver Crosses or Golden Crosses. As long as the majority of indicators and models are bullish, the current decline is viewed as a correction within a bigger uptrend (bull market environment).

The S&P 500 SPDR (SPY) serves as the base-case for a correction and I would expect the majority of stocks and stock-related ETFs to follow SPY. The pennant, rising 200-day SMA and 33% retracement line converge in the 310-320 area for a target zone. It is also normal for a return to the rising 200-day after an initial break. A 13% decline to the 310 area may seem extreme, but remember that SPY is digesting a 64% advance (three steps forward). One step backward would retrace a third of this move.

Medium-term Indicators are Net Bullish

Strong trends in one direction or another produce relatively consistent indicator signals (all bullish or all bearish). Indicator signals often turned mixed and whipsaw during counter-trend moves and trading ranges. Counter-trend moves are bounces within a bigger downtrend and pullbacks within a bigger uptrend (corrections). SPY is currently in some sort of correction right now and the more sensitive indicators are whipsawing.

On the bullish side, the High-Low Lines are rising, the %Golden-Cross lines are rising, the %Silver-Cross lines remain above their bullish thresholds and two of the three Bullish Percent Indexes remain bullish. 20-day High-Low Percent and the Volatility indicators triggered back to bullish again this week. These two are the most sensitive of the group and more prone to whipsaws

The percentage of stocks with silver crosses (20-day EMA above 50-day EMA) remains bullish overall, but the percentage has been steadily declining since mid August. This is short-term bearish and supports the argument for a correction in SPY. Longer term, all four remain above 40% and have yet to cross below their bearish thresholds.

The next chart shows the percentage of stocks with golden crosses. Nasdaq 100 %Golden-Crosses moved above its 20-day EMA in late April and moved above 80% in late July. The indicator flattened over the last seven weeks, but remains at relatively high levels and bullish. Perhaps a move below 70% would be negative. SPX and MID %Golden-Crosses followed with moves above the 20-day EMA in early May, while SML %Golden-Crosses finally joined in mid May. All three lines are rising and above their 20-day EMAs (bullish until proven otherwise).

The High-Low Lines are still rising because the histograms are positive. These histograms show the difference between the High-Low Line and its 10-day EMA.

The Bullish Percent Indexes remain mixed with the Nasdaq 100 BPI moving below 40% to turn bearish last week. The S&P 500 and S&P 100 BPIs remain above 60% and did not come close to triggering bearish.

20-day High-Low Percent whipsawed this week with a move above +10%. This is a pretty sensitive indicator that is often the first to turn, up or down.

The Volatility indicators moved lower this week and back below 2, which suggests low volatility (bullish). Of course, keep in mind that the S&P 500 fell 1.6% on the open Thursday, advanced 1.3% from 9:35 to 11:15, the fell 1.4% to retest the low by 12:15. All this in less than 3 hours. Sounds volatile to me. (Hat-tip @FrankCappelieri)

9 of 10 Breadth Models Bullish

Four of the five long-term breadth models are bullish (SPX, NDX, OEX and MID). The S&P SmallCap 600 model is net bearish. All five short-term models are bullish.  

Long-term Breadth Models

  • – S&P 500: bullish since 23-Jul
  • – Nasdaq 100: bullish since 18-May
  • – S&P 100: bullish since 2-Jul
  • – S&P MidCap 400: bullish since 10-Aug
  • – S&P SmallCap 600: bearish since  25-Feb

Short-term Breadth Models

  • – S&P 500: bullish since 23-Jul
  • – Nasdaq 100: bullish since 29-Apr
  • – S&P 100: bullish since 26-May
  • – S&P MidCap 400: bullish since 9-Apr
  • – S&P SmallCap 600: bullish since 9-Apr

Even though small-caps and mid-caps led the initial surge off the March lows, large-caps and large-cap techs took over and dominated on the way to new highs. The Nasdaq 100 long-term breadth model was the first to turn bullish (18-May) and the S&P 100 model followed with a bullish signal on 2-July. Today I will focus on the S&P 100 breadth models because these 100 stocks are the biggest drivers of the S&P 500. Also note that 26 stocks in the Nasdaq 100 are in the S&P 100 ($OEX). OEX is the 800 pound gorilla in the room and its breadth indicators should be watched closely.

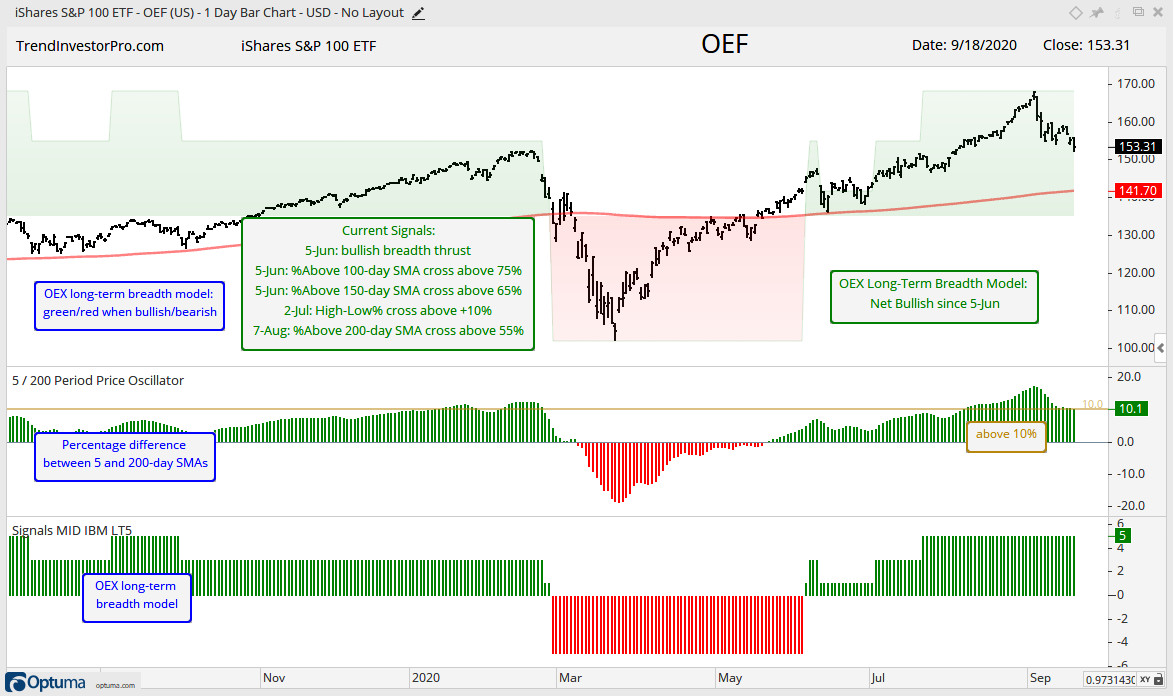
The first chart shows the S&P 100 ETF (OEF) with the 5-indicator long-term breadth model overlay. The model is green when net bullish and red when net bearish. The bottom window shows the model with the actual levels. +3 means 4 indicators are bullish and 1 bearish (4 – 1 = +3). Currently, all five indicators are bullish.

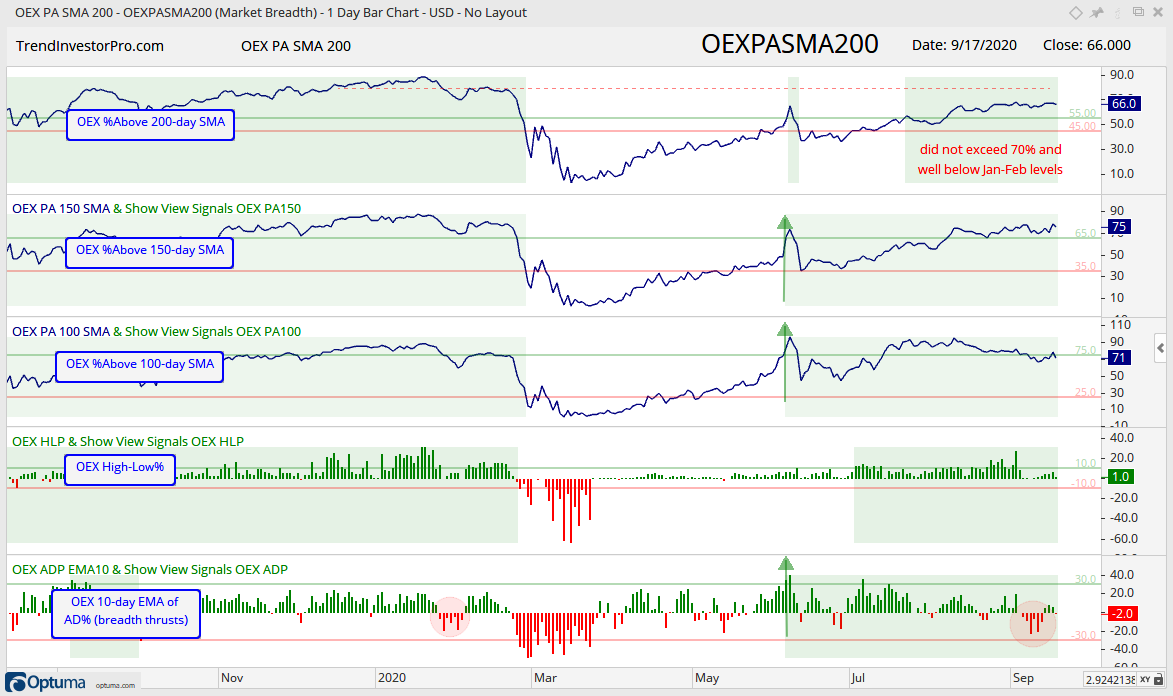
The next chart shows the individual indicators that make up the breadth model and the signal levels with the red and green lines. The model signals are shaded green when bullish and unshaded when bearish. This model caught the February downturn in timely fashion, but was late to the rebound party and did not turn bullish until OEF was above its 200-day. The %Above 150-day, %Above 100-day and 10-day EMA of Advance-Decline Percent were the first to trigger and turn the model bullish in early June (green arrows).

The model remains fully bullish, but we can see that %Above 200-day SMA did not clear 70%, even when OEF was hitting new highs. Fewer stocks moved into long-term uptrends in August-September, as opposed to November-February when this indicator exceeded 80%. The red ovals on the 10-day EMA of AD% highlight the dip in early January and the dip in early September. These dips were not enough to trigger a bearish breadth thrust, which requires a move below -30%. The September dip, however, was fairly strong and showed the most downside participation since late March.

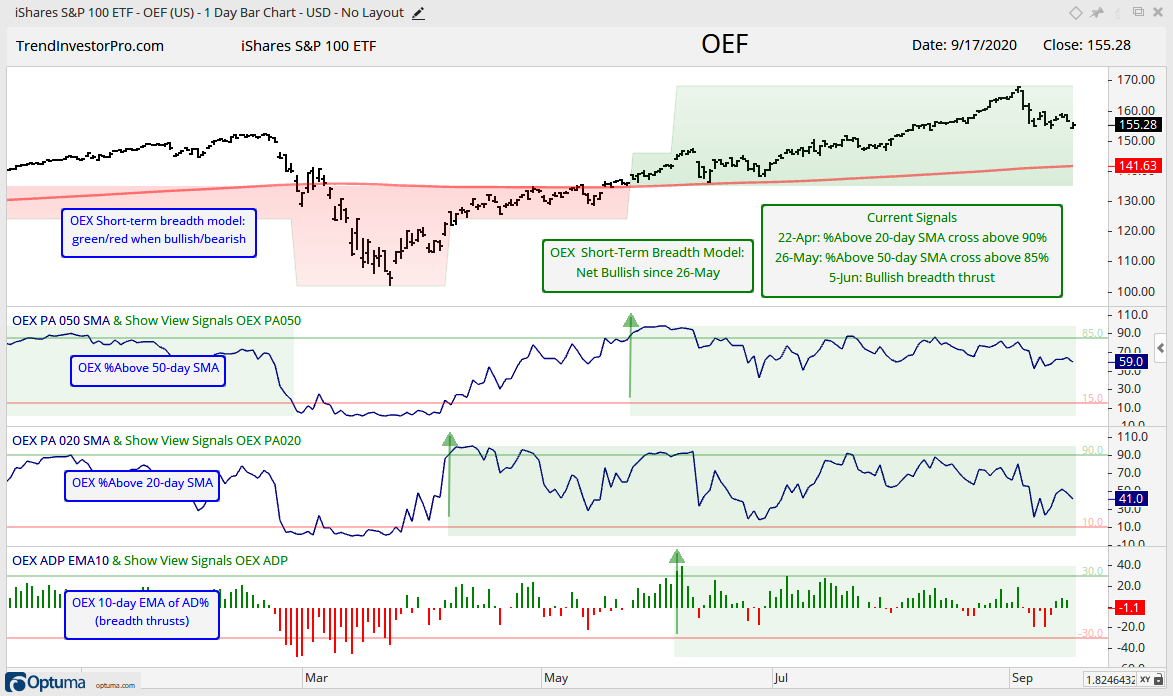
The next chart shows the short-term breadth model and indicators for the S&P 100. The model turned bullish on 26-May. Notice how %Above 20-day SMA surged above 90% in late March to signal the first breadth thrusts of sorts. The %Above 50-day SMA exceeded 85% on 26-May to turn the model net bullish.

All three indicators are currently bullish, but we have seen some deterioration over the last few months. Individual bearish breadth thrusts would trigger if %Above 50-day SMA moves below 15%, %Above 20-day SMA moves below 10% and the 10-day EMA of AD% moves below -30% (red lines). The early September decline was a warning shot and a follow through decline from here could tilt the balance. Stay tuned…

You can learn more about the breadth model and its historical performance in this article and video (here).

No Change in the Sector Breadth Model

Stocks firmed this week with the Materials SPDR (XLB) and Industrials SPDR (XLI) leading the chart. Advance-Decline Percent for these two sectors was positive the last five days straight. AD% for the other nine sectors was mixed. All three breadth indicators are already bullish for XLB and XLI so these moves did not reverse any signals.

Overall, seven of eleven sectors are net bullish with five of the top six sectors net bullish. This is enough to support the long-term uptrend in SPY and bull market environment. Finance is the only one of the big sectors that is net bearish. Utilities and REITs are also net bearish, as is Energy. XLF accounts for 10% of the S&P 500, while XLU, XLRE and XLE each weigh less than 3%. Yes, they are small and have little effect on SPY, which is dominated by large-caps and big sectors.

Bonds and Bond Proxies

XLU and XLRE are bond proxies because they have relatively high yields, 3.24% and 3.09%, respectively. For reference, SPY yields 1.8%, QQQ yields 1.44%, VIG yields 1.71% and the yield on the 30-year is around 1.4%. Yes, SPY yields more than the Dividend Appreciation ETF (VIG). In a world where there is no alternative to stocks (TINA), the yields on XLU and XLRE seem pretty juicy.

The chart below shows TLT, XLU and XLRE for comparison. XLU and XLRE may be bond proxies, but they are still stocks. The green line shows when all three moved higher (SPY also moved higher). The red line shows when XLU and XLRE moved lower along with SPY. The blue line shows when all three moved sideways from mid April to mid September.

Short-term, TLT broke out of a wedge and I am waiting for follow thru above the early September high. XLU broke out of a falling flag and this breakout is largely holding, despite lack of follow through. XLRE hit its highest level since early June with a breakout in early September, but did not follow through either. The green lines mark support for all three.

Two things to keep in mind. First, TLT is the only real alternative to stocks. A decline in stocks, however, does not guarantee an advance in TLT, but it certainly increases the odds for a move higher. Second, XLU and XLRE are still part of the stock market and may not be immune to broad market weakness. Correlations among sectors tend to rise when SPY declines.

Yield Spreads and the Fed Balance Sheet

There is no real change in the AAA or BBB bond spreads. Both fell back to their pre-crisis levels and stabilized. The red lines mark my subjective lines in the sand. A move above 1 in the AAA spread and 2 in the BBB spread would show some stress in the credit markets and be negative.

The Junk bond spread fell back below its pre-crisis highs and stabilized the last few months. Stabilization at relatively low levels is ok. An upturn would not be ok. A move above 6 would show stress in the junk bond market and be negative for stocks. Note that junk bonds act more like stocks because they are tied to the economy. Unless, of course, there is an invisible hand buying up junk.

The Fed balance sheet continues to inch higher, if you consider a $54 billion increase inching higher. Of course, the increase over the last ten weeks looks small relative to the $3 trillion increase from March to May. The Fed took its foot off the gas pedal for a few weeks (mid June to early July) and then put its foot back on in mid July (green shading).

Thanks for tuning in and happy Friday!

ETF Trends, Patterns and Setups – SPY and QQQ Look Vulnerable, Bond Proxies Catch a Bid, Gold Stalls as Dollar Firms

There’s been a shake up this week. A handful of equity-related ETFs are in the top group, as far as the trend, patterns and setups are concerned. However, I downgraded several groups because it looks like SPY and QQQ are moving further into correction mode. The majority of stock-related ETFs will be under pressure should SPY correct and the majority of tech-related ETFs will be under pressure should QQQ correct.

ETF Trends, Patterns and Setups – SPY and QQQ Look Vulnerable, Bond Proxies Catch a Bid, Gold Stalls as Dollar Firms Read More »

Update for Precious Metals (GDX, GLD, SLV), Healthcare (XLV, IBB, XBI) and Bond Proxies (TLT, XLU, XLRE)

Tech-related ETFs continue to drag their feet and remain in corrective mode. This puts the attention elsewhere and biotechs are picking up the slack. Namely, the Biotech ETF (IBB) and Biotech SPDR (XBI) made bids to end their corrections and resume their bigger uptrends. Elsewhere, precious metals related ETFs bounced within their consolidations and bond proxies popped with XLU and XLRE getting big moves.
Update for Precious Metals (GDX, GLD, SLV), Healthcare (XLV, IBB, XBI) and Bond Proxies (TLT, XLU, XLRE) Read More »

Timing Models – Accelerations, Trend Shocks, Indicators turn Mixed, Downside Targets and Breadth Models

The stock market was overextended in late August and the bulls gave it one more push higher with a small acceleration higher into late September. Technically, an acceleration higher signals an increase in momentum, which can be bullish. However, as with most technical signals, perspective is needed for interpretation. Today we will look at the accelerations that led to a reversal and the outsized decline. What do they portend going forward?

Timing Models – Accelerations, Trend Shocks, Indicators turn Mixed, Downside Targets and Breadth Models Read More »

ETF Grouping and Ranking Report – Outsized Declines, Retracement Targets, Patience During Corrections, Gold and Bonds Balk

Stocks were hit hard from Friday to Tuesday with the S&P 500 SPDR, Nasdaq 100 ETF and others recording outsized declines. Today we start with these outsized declines and show what they entail going forward. Stocks were already extended and these sharp declines signal the start of a corrective period. At this point, I will treat any weakness in SPY and QQQ as a correction within a bigger uptrend.

ETF Grouping and Ranking Report – Outsized Declines, Retracement Targets, Patience During Corrections, Gold and Bonds Balk Read More »

Timing Models – Bears Fire a Shot, SPY Tags and Pulls Back, Volatility Ticks Up and Breadth Model Review

The bears fired a shot across the bow, but one or two days is not enough to reverse a strong uptrend. There were already warnings of a correction or pullback because SPY has been more than 10% above its 200-day since August 12th and QQQ has been 20% above its 200-day since July 6th. Of course, overbought indicators are not very good for timing a correction. In fact, I have yet to find a good indicator for timing a peak/pullback during a strong uptrend.

Timing Models – Bears Fire a Shot, SPY Tags and Pulls Back, Volatility Ticks Up and Breadth Model Review Read More »

ETF Trend/Pattern Grouping – Overextended get More So, Flag Breakouts, Pennants, Falling Wedges and Bollinger Band Squeezes

Overextended its an incredibly nebulous term. Many ETFs were considered overextended last week and simply became even more so as strong buying pressure persisted. This is a classic case of becoming overbought and remaining overbought because the uptrend is strong. These ETFs, which are in the first few groups, are in the trend-monitoring phase.

ETF Trend/Pattern Grouping – Overextended get More So, Flag Breakouts, Pennants, Falling Wedges and Bollinger Band Squeezes Read More »

Timing Models – Overextended, but Breadth and Medium-term Indicators Support Current Upswing

We all know that the S&P 500 is driven by large-caps, especially the big four, which account for over 20% of the index (AAPL, MSFT, AMZN, GOOGL). Furthermore, most of us are aware that breadth measures are not as strong as the S&P 500 and this is reflected in the S&P 500 EW ETF (RSP), which has yet to clear its June high. Breadth, however, is not exactly weak. It is just strong enough to sustain the advance. In other words, the cup is half full, not half empty.

Timing Models – Overextended, but Breadth and Medium-term Indicators Support Current Upswing Read More »

ETF Trend/Pattern Ranking and Grouping – Strong Extensions, Second Winds, Modest Extensions, Corrective Patterns, Laggards and Breakdowns

Stock-related ETFs remained strong and many so-called overbought ETFs became even more overbought as their uptrends extended. Many ETFs are in the trend-monitoring or waiting phase. The early breakouts occurred in July and these ETFs followed through with further gains the last several weeks. Some tech-related ETFs stalled in late July and early August, but caught a second wind with breakouts over the last few weeks.

ETF Trend/Pattern Ranking and Grouping – Strong Extensions, Second Winds, Modest Extensions, Corrective Patterns, Laggards and Breakdowns Read More »

Timing Models – SPY Tags a New High, Medium-term Indicators Favor the Bulls and SPX Breadth Model Remains Bullish

The bulk of the evidence remains bullish for large-caps, large-cap techs and mid-caps, but mixed for small-caps. I am also seeing mixed performance within the S&P 500, especially when looking at the equal-weight sectors. Technology, Healthcare and Consumer Discretionary remain strong, while Finance, Energy and REITs are weak. Finance is the only big sector that shows underlying weakness though.
Timing Models – SPY Tags a New High, Medium-term Indicators Favor the Bulls and SPX Breadth Model Remains Bullish Read More »

ETF Trend/Pattern Video – Bonds Oversold, Gold Turns Volatile, XLY Holds Chandelier, REITs Vulnerable and Dollar Springs Bear Trap

Today’s video will focus on the core ETF charts. We will start with the scatter plot and see that the bond ETFs in the upper left, which means they are oversold and in uptrends. On the ranking tables, ETFs related to Consumer Discretionary, Healthcare and Technology are leading. I continue to follow the Chandelier Exits for several ETFs as their uptrends extend (XLY, ITB, XRT). Elsewhere

ETF Trend/Pattern Video – Bonds Oversold, Gold Turns Volatile, XLY Holds Chandelier, REITs Vulnerable and Dollar Springs Bear Trap Read More »

ETF Ranking, Grouping and Analysis – Mean-Reversion Setups in Bond ETFs, Bounces in Biotech ETFs and Breakouts in Two Healthcare ETFs

Despite the usual pockets of weakness, there is still plenty of strength out there in ETF land. Housing, Retail and Consumer Discretionary ETFs moved to new highs. Tech-related ETFs remain mixed with some hitting new highs and some moving back into their consolidation patterns. Precious metals ETFs got sizable mean-reversion bounces, but it looks like volatility is picking up in this group.

ETF Ranking, Grouping and Analysis – Mean-Reversion Setups in Bond ETFs, Bounces in Biotech ETFs and Breakouts in Two Healthcare ETFs Read More »

Q&A – How to Use the ETF Rankings, RSI65 versus StochClose, Settings for Chandelier Exits and Trend-Timing the Broader Market

I received some pertinent questions over the weekend and create a post to share the answers. My email answers were not as detailed as in this post, which provides more details and examples. The first question deals with the StochClose ranking and how to use it. This answer will also highlight seven broad trading strategy groups. Second

Q&A – How to Use the ETF Rankings, RSI65 versus StochClose, Settings for Chandelier Exits and Trend-Timing the Broader Market Read More »

Timing Models – Participation Broadens as Two Key Sectors Perk Up and Mid-cap Breadth Improves

Even though the current advance is getting quite extended, the broad market environment remains bullish and the medium-term uptrends rule. Tech-related ETFs and stocks drove the market higher from late March to late June. Even though the tech surge slowed, participation broadened over the last six weeks as other groups picked up the slack. The Industrials SPDR (XLI) is the top performing sector since July 1st

Timing Models – Participation Broadens as Two Key Sectors Perk Up and Mid-cap Breadth Improves Read More »

ETF Ranking and Grouping – Uptrends, Overbought Conditions, Pullbacks and Breakout Failures

There are still a lot of uptrends out there in ETF land, and this includes some key stock-related ETFs. Nevertheless, we are seeing some rotation at work the last few weeks. The tech-related ETFs slowed their advance and some even failed to hold their breakouts. Meanwhile, ETFs related to consumer discretionary continued higher and are leading the pack. However, some of these new leaders are getting extended (XLY, XHB).

ETF Ranking and Grouping – Uptrends, Overbought Conditions, Pullbacks and Breakout Failures Read More »

Timing Models – Falling Volatility Powers SPY and Breakouts Hold, but Participation Continues to Wane

The chart below shows year-to-date performance for the top 20 stocks in the S&P 500. Overall, the year is mixed with eleven up and nine down. Amazon is up over 70%, Apple is up over 50% and Microsoft is up over 30%. Facebook and Home Depot are dragging their feet with gains greater than 20%. As strong as the stock market seems, strength is clearly concentrated in a few stocks. Moreover, these few stocks are up big, really big.

Timing Models – Falling Volatility Powers SPY and Breakouts Hold, but Participation Continues to Wane Read More »

ETF Ranking and Grouping – Breakouts Hold, Small-caps Come to Life, Banks and Energy Still Lagging

After some volatility and big moves in March, April and May, trading has turned downright boring the last few weeks. Nevertheless, the majority of breakouts are holding and there are plenty of leaders. Tech, housing, retail, precious metals and Healthcare continue to lead. ETFs related to Finance and Energy continue to lag. Industrials and small-caps perked up this week and extended on their breakouts, which were looking rather feeble just last week.

ETF Ranking and Grouping – Breakouts Hold, Small-caps Come to Life, Banks and Energy Still Lagging Read More »

Timing Models – Participation Wanes, but Medium-term Uptrends and Short-term Breakouts Hold

There are times for setups and signals, and there are times to wait. The waiting game is either waiting for the next setup/signal to materialize or monitoring the current signal in play. At this stage, we are in the monitoring stage for several signals that triggered in the first half of July.

Timing Models – Participation Wanes, but Medium-term Uptrends and Short-term Breakouts Hold Read More »

Timing Models – Medium-term Uptrends, Short-term Breakouts and QQQ Exuberance

My current focus remains on the medium-term up trends, which began with the surge in late March. The bulls are still in control of these medium-term trends and we saw several short-term breakouts in July. Some breakouts were strong as price exceeded the June high (SPY), while some were feeble as price remains well below the June high (RSP). Strong or feeble, the breakouts are still holding and have yet to be proven otherwise.

Timing Models – Medium-term Uptrends, Short-term Breakouts and QQQ Exuberance Read More »

Scroll to Top