

The next report will be on Thursday, April 24th.
Report Headlines
- SPY in Downtrend and Breadth Net Bearish since March 12th
- QQQ in Downtrend and Breadth Net Bearish since March 31st
- RSP in Downtrend and Breadth Net Bearish since March 11th
- Yield Spreads Remain Wide (stress)
- Fed On Hold as Short-term Yields Remain Flat
- Yields Break Out as Bonds Break Down
Evidence is Bearish and the 10yr Yield is Rising
There is no change for the long-term trends and breadth charts. This group has been net bearish since mid March. SPY, QQQ and the S&P 500 EW ETF (RSP) are in long-term downtrend since early-mid March. Six of the nine breadth indicators were bearish as of mid March. The other three followed suit and all nine breadth indicators are currently bearish.
The trend indicator (Bollinger Bands 125,1) and breadth indicators generate long-term trend-following signals. This means they will not catch the top or the bottom. Instead, they generate signals when there is a significant (trend changing) move. We saw a lot of technical damage from mid March to early April, and it will take time to heal. For example, 31% of S&P 500 stocks are above their 200-day SMA. We can start thinking bull market when this number gets above 60%.
The bond market and Fed policy are the wild cards. The 10-yr Treasury Yield broke out of a falling channel, while the 7-10 Yr Treasury Bond ETF (IEF) broke rising channel support. This is bearish for bonds and argues for higher yields, which would be negative in a bear market. We also see that the 3-month Treasury Yield remains flat because the Fed is stuck. The Fed has yet to turn hawkish, but flat short-term rates mean the Fed is on hold. Normally we see short-term rates falling in a bear market.
SPY in Downtrend and Breadth Net Bearish since March 12th
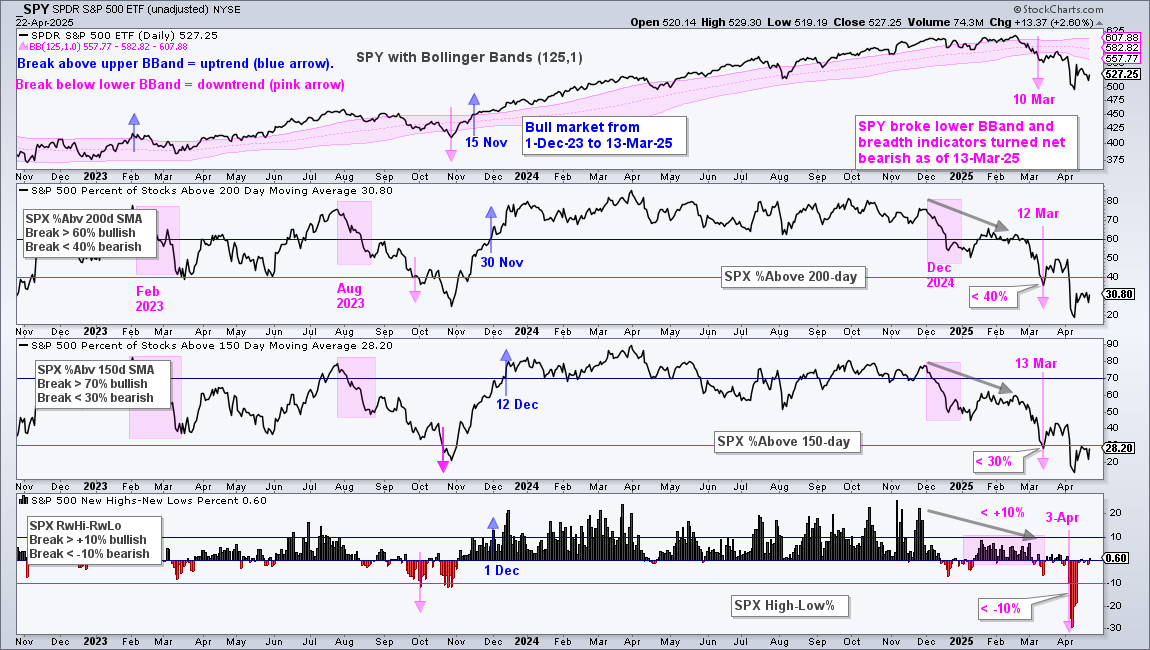
SPY moved into a downtrend on March 10th and the breadth indicators turned net bearish on March 12th (2 of 3). The third breadth indicator, S&P 500 High-Low% ($SPXHLP), triggered bearish on March 31st.
- SPY broke the lower Bollinger Band (125,1) on March 10th
- SPX %Above 200-day SMA broke below 40% on March 12th
- SPX %Above 150-day SMA broke below 30% on March 12th
- SPX High-Low Percent Hit -10% on April 3rd
About the Major index ETFs and Breadth Signals
The top window on each breadth chart shows the corresponding major index ETF with Bollinger Bands (125,1). An uptrend signals when the ETF breaks above the upper Bollinger Band and a downtrend signals with a break below the lower band. The index ETFs are the S&P 500 SPDR (SPY), the Nasdaq 100 ETF (QQQ) and the S&P 500 EW ETF (RSP).
Each index has three breadth indicators. SPY uses S&P 500 breadth, QQQ uses Nasdaq 100 breadth and RSP uses S&P 1500 breadth. The percentage of stocks above the 200-day SMA triggers bullish with a move above 60% and bearish with a move below 40%. The percentage of stocks above their 150-day SMAs triggers bullish with a move above 70% and bearish with a move below 30%. High-Low Percent triggers bullish with a move above +10% and bearish with a move below -10%. High-Low Percent is the percentage of stocks making 52-week highs less the percentage making 52-week lows.
These bullish/bearish signal thresholds are designed to identify significant changes in the stock market (bull market or bear market). As trend-following signals, they will lag and there will be whipsaws. Long-term, these signals keep us on the right side of the market. The idea is to be invested during bull markets (risk-on) and in cash during bear markets (risk-off).
QQQ in Downtrend and Breadth Net Bearish since March 31st
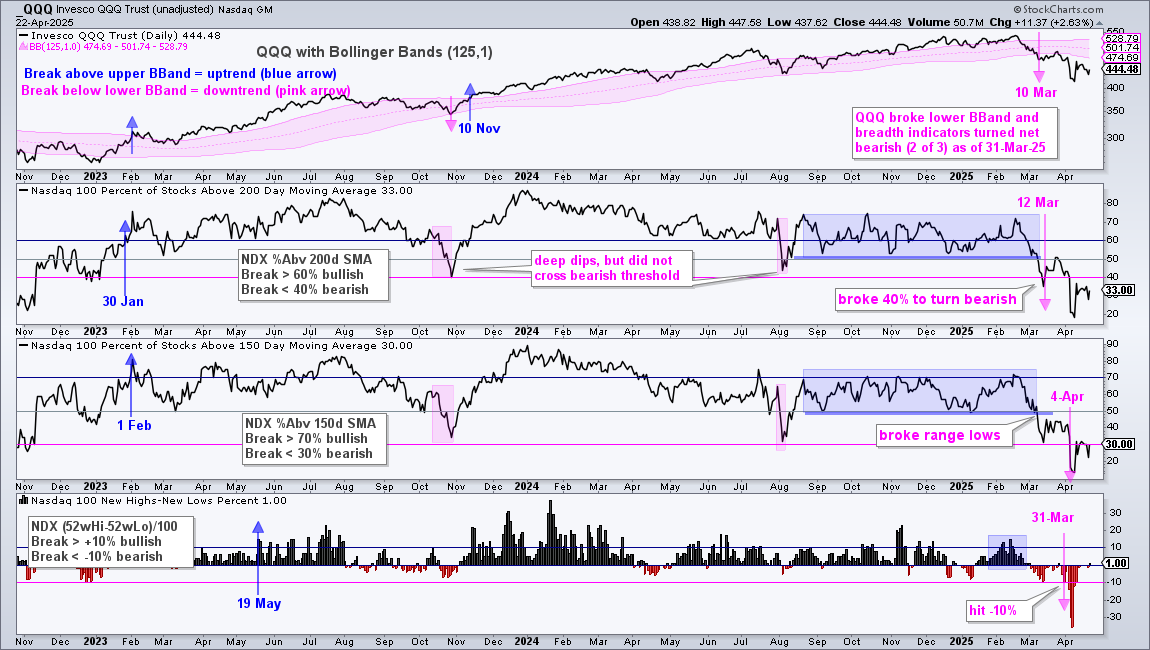
QQQ moved into a downtrend on March 10th and the breadth indicators turned net bearish on March 31st (2 of 3). The third breadth indicator, Nasdaq 100 Percent Above 150-day SMA ($NDXA150R), triggered bearish on April 4th.
- QQQ broke the lower Bollinger Band (125,1) on March 10th
- NDX %Above 200-day SMA broke below 40% on March 12th
- NDX %Above 150-day SMA broke below 30% on April 4th
- NDX High-Low Percent Hit -10% on March 31st
RSP in Downtrend and Breadth Net Bearish since March 11th
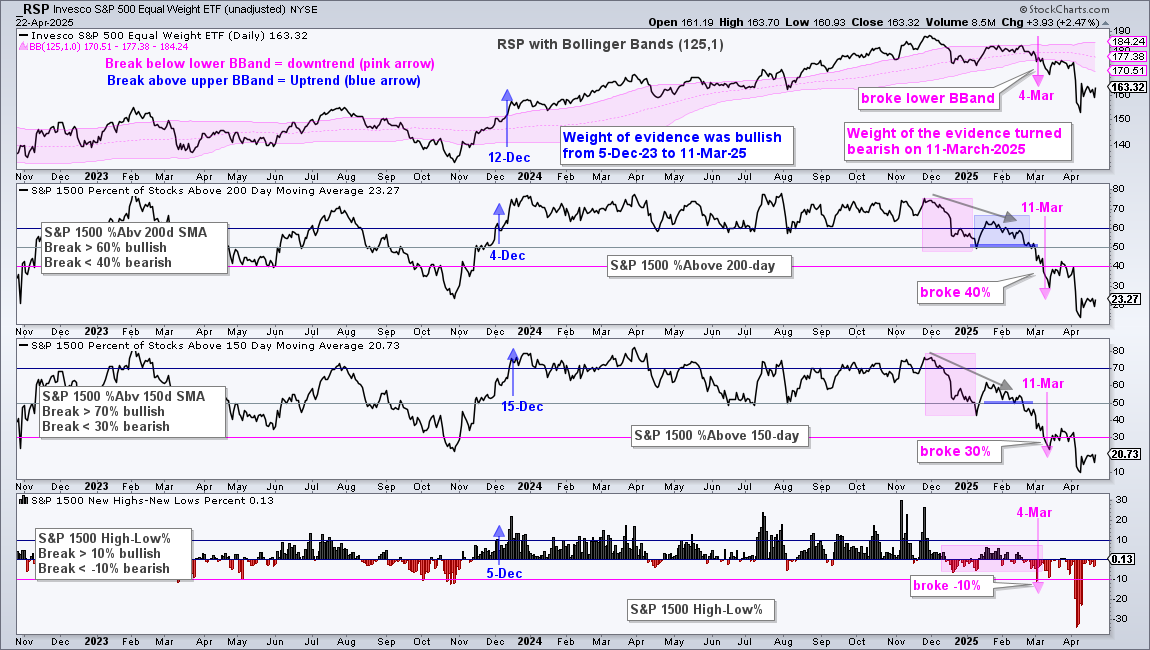
The S&P 500 EW ETF (RSP) moved into a downtrend on March 4th and the breadth indicators turned net bearish on March 11th (3 of 3).
- RSP broke the lower Bollinger Band (125,1) on March 4th
- S&P 1500 %Above 200-day SMA broke below 40% on March 11th
- S&P 1500 %Above 150-day SMA broke below 30% on March 11th
- S&P 1500 High-Low Percent broke below -10% on March 4th
Yield Spreads Remain Wide (stress)
The chart below shows SPY, the Junk Bond Spread ($$HYIOAS) and the BBB Bond Spread ($$BBBOAS). Both spreads broke out in mid March and widened (rose) in April, hitting their highest levels since 2023. There was a reprieve as stocks stabilized the last two weeks, but these spreads remain at levels that reflect stress in the credit markets (still wide). This sharp widening is comparable to what we saw during the 2022 bear market. Bond traders are demanding a higher risk-premium to hold corporate bonds (vs lower risk Treasury bonds). This means they are more concerned with the economy and the issuer’s ability to repay its obligation, which is negative for stocks.
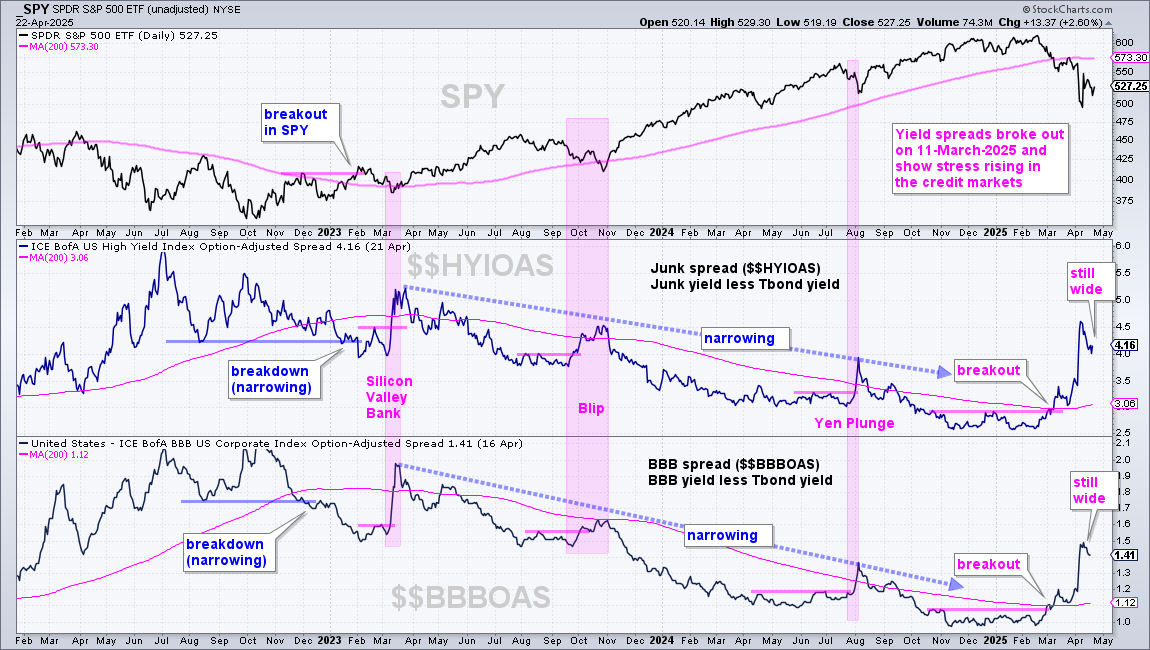
The yield spread is the difference between the Junk Bond Yield or BBB Bond Yield and a comparable Treasury Bond Yield. Junk and BBB bonds represent risk assets, while Treasuries represent relative safe-havens. The spread is the risk premium for holding the riskier assets. Narrow/narrowing spreads show confidence and this is bullish for stocks. Wide/widening spreads show stress and this is negative for stocks.
Fed On Hold as Short-term Yields Remain Flat
The top window shows the 3-month Treasury Yield ($UST3M) falling from July to December and then moving sideways in 2025 (four months). This means the Fed was dovish from July to December and then went on hold in 2025. While it is hard to call the Fed dovish at this point, the Fed is clearly not turning hawkish because this short-term yield remains below 4.5%. A decline from here would show a return to dovishness, while a breakout at 4.5% would suggest a hawkish Fed. The assumption here is that the bond market and short-term rates lead the Fed and foreshadow policy.
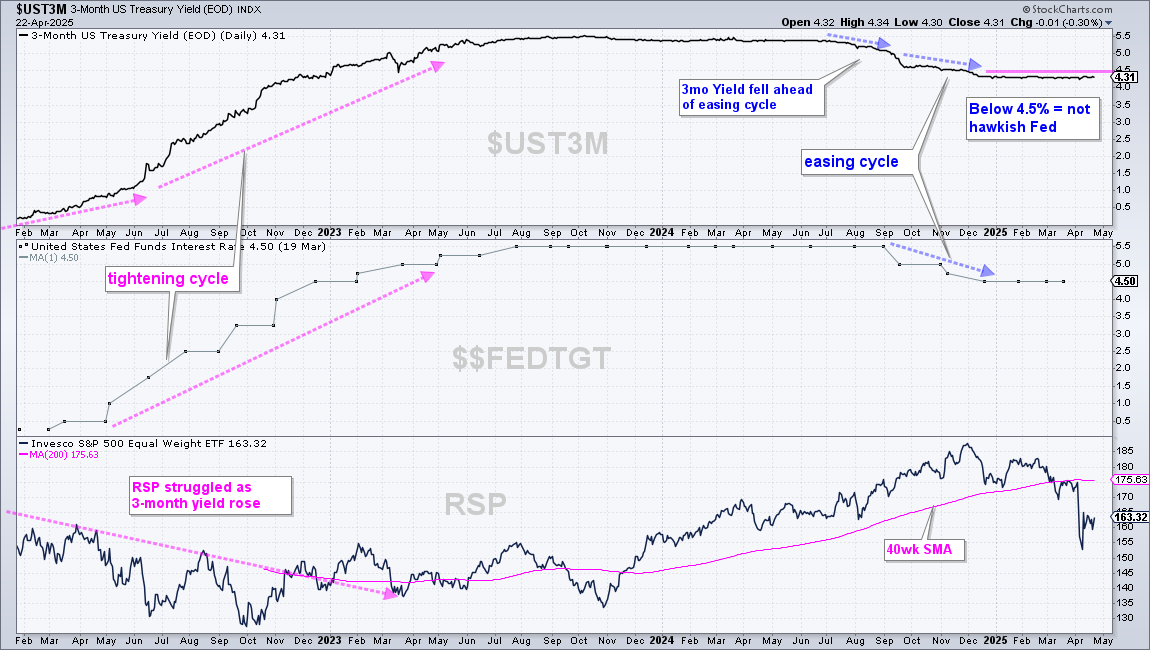
The middle window shows the Fed Funds Target Rate ($$FEDTGT) falling from September to December as the Fed cut rates (dovish). This Fed Funds target rate flattened this year, but has yet to turn up, which means the Fed has yet to raise rates (officially change their stance).
Several factors influence short-term Treasury yields, but they are still closely aligned with Fed policy and often lead the Fed. This means the yield often peaks (troughs) and turns down (up) before the Fed starts to lower (raise) rates. We use the 3-month Treasury yield to identify current Fed policy and anticipate the next Fed move
Yields Break Out as Bonds Break Down
The chart below shows weekly candlesticks for the 10-yr Treasury Yield ($TNX) and 7-10 Yr Treasury Bond ETF (IEF). $TNX broke out of a falling wedge in December, corrected with a pullback from January to March and broke out with a long white candlestick in early April. The yield stalled after this breakout, but the breakout remains bullish and targets a move towards 50 (5%).
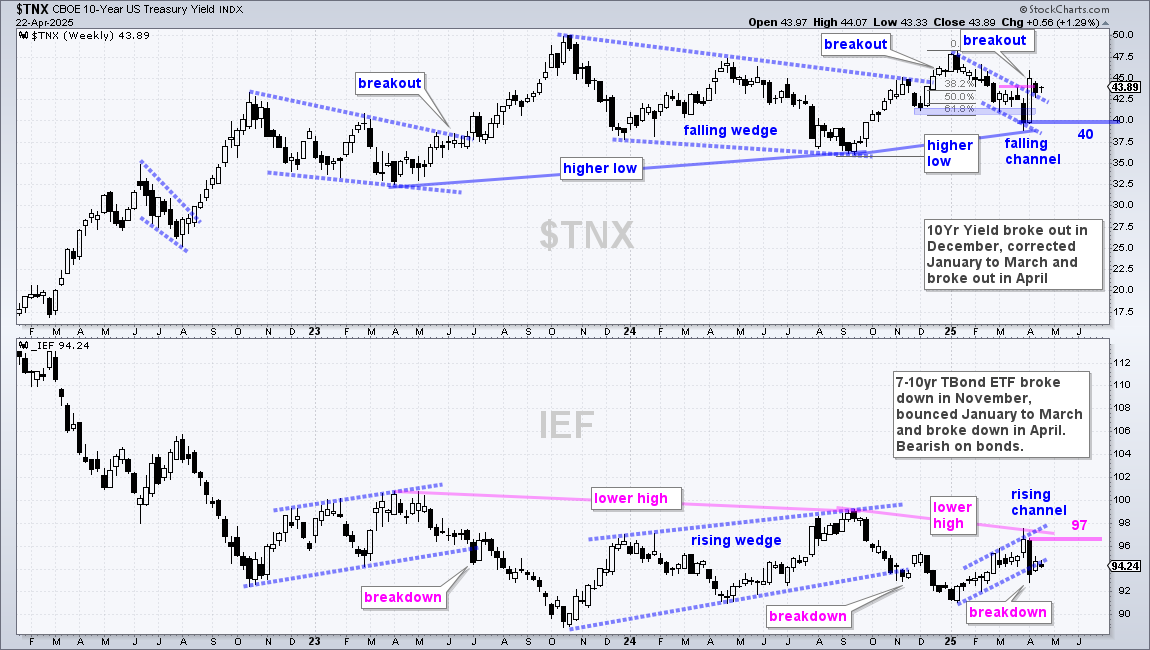
IEF sports a mirror image because bonds fall when yields rise. IEF broke down in November, rebounded with an advance from January to March and broke down again in April. I view the rising channel has a bearish continuation pattern and the breakdown signals a continuation of the September-December decline. The ETF also lower highs from April 2023 to September 2024 and September 2024 to March 2025 (pink lines). There is clearly a long-term downward bias in IEF. Re-evaluation resistance is set at 97.
Several factors influence long-term Treasury yields, including growth expectations, inflation expectations, government debt levels, tariffs and foreign bond holders. The 10-yr Treasury Yield typically falls when the economic outlook dims and/or inflation expectations rise. Conversely, the yield typically rises when the economic outlook is bright and/or inflation expectation fall.